Skip to content

Posts tagged ‘ERP’

Cloud Computing and Enterprise Software Forecast Update, 2012

The latest round of cloud computing and enterprise software forecasts reflect the growing influence of analytics, legacy systems integration, mobility and security on IT buyer’s decisions.

Bain & Company and Gartner have moved beyond aggregate forecasts, and are beginning to forecast by cloud and SaaS adoption stage.  SAP is using the Bain adoption model in their vertical market presentations today.

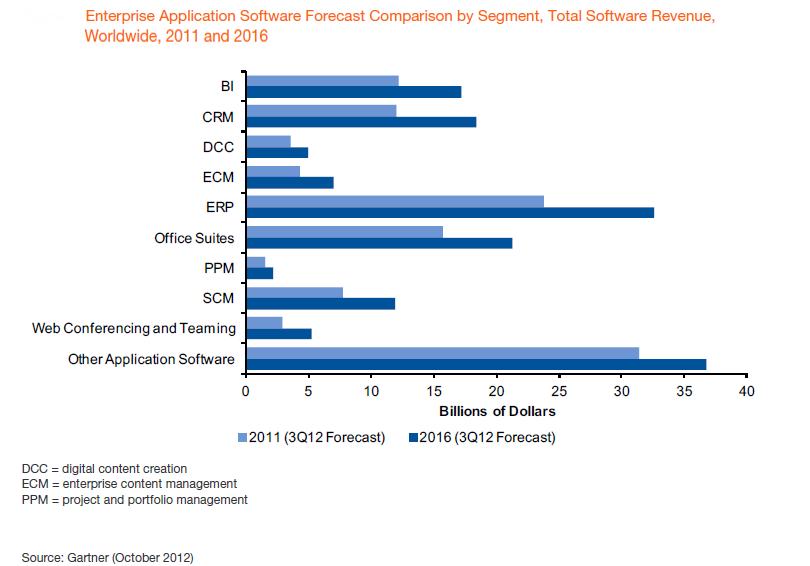
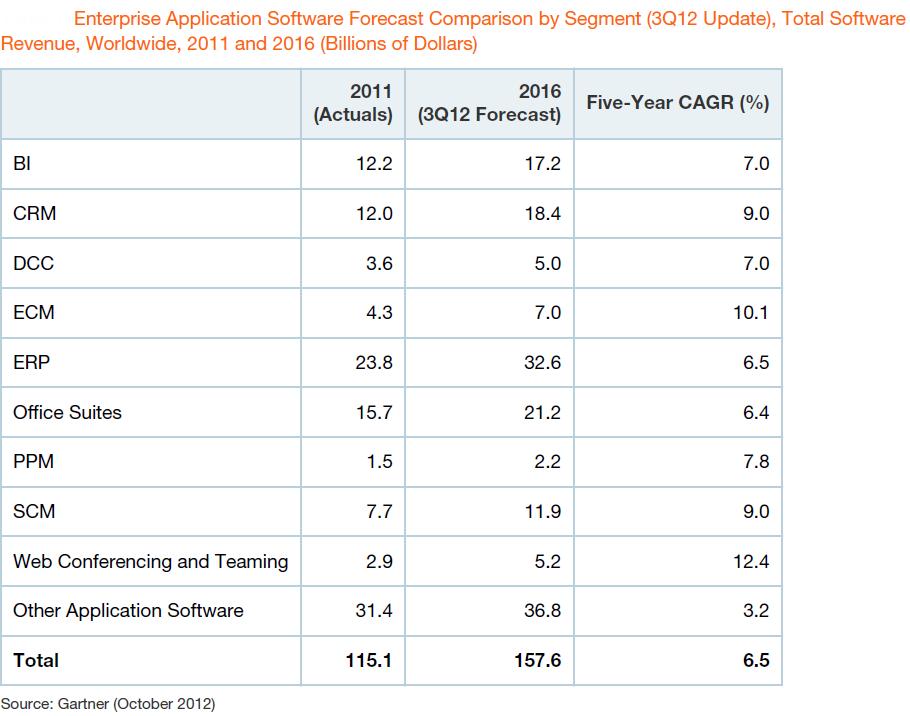
Despite the predictions of the demise of enterprise software, forecasts and sales cycles I’ve been involved with indicate market growth.  Mobility and cloud computing are the catalysts of rejuvenation in many enterprise application areas, and are accelerating sales cycles.  Presented in this roundup are market sizes, forecasts and compound annual growth rates (CAGRS) for ten enterprise software segments.

Key take-aways from the latest cloud computing and enterprise software forecasts are provided below:

  • Public and private cloud computing will be strong catalysts of server growth through 2015.  IDC reports that $5.2B in worldwide server revenue was generated in 2011 or 885,000 units sold.  IDC is forecasting a $9.4B global market by 2015, resulting in 1.8 million servers sold. Source:  IDC Worldwide Enterprise Server Cloud Computing 2011–2015 http://www.idc.com/getdoc.jsp?containerId=228916 
  • IDC reports that enterprise cloud application revenues reached $22.9B in 2011 and is projected reach $67.3B by 2016, attaining a CAGR of 24%.  IDC also predicts that by 2106, $1 of every $5 will be spent on cloud-based software and infrastructure. Report, Worldwide SaaS and Cloud Software 2012–2016 Forecast and 2011 Vendor Shares, Link: http://www.idc.com/getdoc.jsp?containerId=236184
  • 11% of companies are transformational, early adopters of cloud computing, attaining 44% adoption (as defined by % of MIPS) in 2010, growing to 49% in 2013.  This same segment will reduce their reliance on traditional, on-premise software from 34% to 30% in the same period according to Bain & Company’s cloud computing survey results shown below.  SAP is using this adopter-based model in their vertical market presentations, an example of which is shown here.

  • The global Platform-as-a-Service (PaaS) market is growing from $900M in 2011 to $2.9B in 2016, achieving a 26.6% CAGR.  At this projected rate, PaaS will generate an average of $360M a year in revenue between 2011 and 2016.  Gartner projects that the largest segments will be Application Platform Services (aPaaS) which generated 35% of total PaaS spending in 2011, followed by cloud application lifecycle services (12.5).    Source: Market Trends: Platform as a Service, Worldwide, 2012-2016, 2H12 Update Published: 5 October 2012 ID:G00239236.

  • The three most popular net-new SaaS solutions deployed are CRM (49%), Enterprise Content Management (ECM) (37%) and Digital Content Creation (35%).  The three most-replaced on-premise applications are Supply Chain Management (SCM) (35%), Web Conferencing, teaming platforms and social software suites (34%) and Project & Portfolio Management (PPM (33%). The following graphic shows the full distribution of responses. Source: User Survey Analysis: Using Cloud Services for Mission-Critical Applications Published: 28 September 2012

SaaS Adoption Accelerates, Goes Global in the Enterprise

In working with manufacturers and financial services firms over the last year, one point is becoming very clear: SaaS is gaining trust as a solid alternative for global deployments across the enterprise.  And this trend has been accelerating in the last six months.  One case in point is a 4,000 seat SaaS CRM deployment going live in Australia, Europe, and the U.S. by December of this year.

What’s noteworthy about this shift is that just eighteen months ago an Australian-based manufacturer was only considering SaaS for on-premises enhancement of their CRM system.  What changed?  The European and U.S. distribution and sales offices were on nearly 40 different CRM, quoting, proposal and pricing systems.  It was nearly impossible to track global opportunities.

Meanwhile business was booming in Australia and there were up-sell and cross-sell opportunities being missed in the U.S. and European-based headquarters of their prospects. The manufacturer  chose to move to a global SaaS CRM solution quickly.  Uniting all three divisions with a global sales strategy forced the consolidation of 40 different quoting, pricing and CRM systems in the U.S. alone.  What they lost in complexity they are looking to pick up in global customer sales.

Measuring Where SaaS Is Cannibalizing On-Premise Enterprise Applications

Gartner’s Market Trends: SaaS’s Varied Levels of Cannibalization to On-Premises Applications published: 29 October 2012 breaks out the percent of SaaS revenue for ten different enterprise application categories.  The greener the color the greater the adoption.  As was seen with the Australian manufacturer, CRM continues dominate this trend of SaaS cannibalizing on-premise enterprise applications.

Additional take-aways from this report include the following:

  • Perceived lower Total Cost of Ownership (TCO) continues to be the dominant reason enterprises are considering SaaS adoption, with 50% of respondents in 2012 mentioning this as the primary factor in their decision.
  • CRM is leading all other enterprise application areas in net new deployments according to the Gartner study, with the majority of on-premise replacements being in North America and Europe.
  • 95% of Web analytics functions are delivered via the SaaS model  whereas only 40% of sales use cloud today according to the findings of this study.
  • SaaS-based ERP will continued to be a small percentage of the total market, attaining 10% cannibalization by 2012.  Forrester has consistently said this is 13%, growing to 16% by 2015.
  • Office suites and digital content creation (DCC) will attain compound annual growth rates (CAGR) of 40.7% and a 32.2% respectively from 2011 through 2016. Gartner is making the assumption consumers and small businesses will continue be the major forces for Web-based office suites through 2013.
  • The four reasons why companies don’t choose SaaS include uncertainty if it is the right deployment option (36%), satisfaction with existing on-premise applications (30%), no further requirements (33%) and locked into their current solution with expensive contractual requirements (14%).

Bottom Line: Enterprises and their need to compete with greater accuracy and speed are driving the cannibalization of on-premise applications faster than many anticipated; enterprise software vendors need to step up and get in front of this if they are going to retain their greatest sources of revenue.

Source:  Market Trends: SaaS’s Varied Levels of Cannibalization to On-Premises Applications Published: 29 October 2012 written by Chad Eschinger, Joanne M. Correia, Yanna Dharmasthira, Tom Eid, Chris Pang, Dan Sommer, Hai Hong Swinehart and Laurie F. Wurster

Forecasting Public Cloud Adoption in the Enterprise

The economics of public cloud computing are accelerating the pace of change occurring in enterprise software today.

Many of the scenarios that Clayton Christensen insightfully describes in The Innovator’s Dilemma are playing out right now in many sectors of this industry, shifting the balance of purchasing power to line-of-business leaders away from IT.  True to the cases shown in the book, new entrants are bringing disruptive innovations that are being successfully used to attack the most price-sensitive areas of the market.  Winning customers at the low-end and making their way up-market, new entrants are changing the customer experience, economics and structure of the industry.  Salesforce.com is a prime example of how the insights shared in The Innovator’s Dilemma are alive and well in the CRM market for example.  This is an excellent book to add to your summer reading list.

Defining The Public Cloud

The National Institute of Standards and Technology (NIST) have defined the public cloud in their latest definition of cloud computing in their September, 2011 brief you can download here (The NIST Definition of Cloud Computing). The NIST defines public cloud as “the cloud infrastructure is provisioned for open use by the general public. It may be owned, managed, and operated by a business, academic, or government organization, or some combination of them. It exists on the premises of the cloud provider.”   In addition the NIST defines three models including Software as a Service (SaaS), Platform as a Service (PaaS), and Infrastructure as a Service (IaaS).  Gartner’s definition of public cloud computing is comparable yet includes Business Process as a Service (BPaaS) and Cloud Management and Security.

A quick check of the term public cloud on Google Insights shows the rapid ascent of interest in this area.  A graphic from Google Insights is shown below:

Public Cloud Adoption in the Enterprise 

In the many conversations I’ve had with CIOs and CEOs of manufacturing companies the role of cloud computing comes up often.  There’s a very clear difference in the thinking of CIOs who see their jobs as selectively applying technologies to strategic needs versus those who are focused on compliance and risk aversion.  The former see their enterprises moving to public and hybrid clouds quickly to better integrate with dealers, distributors and suppliers at a strategic level.

The public cloud’s pervasiveness in the enterprise is growing rapidly.  This market dynamic is reflected in the report, Forecast: Public Cloud Services, Worldwide, 2010-2016, 2Q12 Update (ID:G00234814).  Gartner breaks out forecasts into the areas of Cloud Business Process Services/Business Process as a Service (BPaaS), Application Services/Software as a Service (SaaS), Application Infrastructure Services/Platform as a Service (PaaS), System Infrastructure Services/Infrastructure as a Service (IaaS) and Cloud Management and Security Services.  Highlights from the report are presented in the following five areas:

Cloud Business Process Services/Business Process as a Service (BPaaS)

  • Gartner is predicting that BPaaS will grow from $84.1B in 2012 to $144.7B in 2016, generating a global compound annual growth rate of 15%.
  • Of the eight subsegments Gartner is tracking in their BPaaS forecast, Cloud Payments (17.8%) Cloud Advertising (17.1%) and Industry Operations (15.1%) are expected to have the greatest compound annual growth rates (CAGR) in revenues generated by 2016.
  • In terms of revenue generated, Cloud Advertising is projected to grow from  $43.1B in 2011 to $95B in 2016, generating 17.1% CAGR in revenue growth through 2016.
  • Cloud Payments are forecast to grow from $4.7B in 2011  to $10.6B in 2016, generating a CAGR of 17.8% worldwide.
  • E-Commerce Enablement using BPaaS-based platforms is expected to grow from $4.7B in 2011 to $9B in 2016, generating a 13.6% CAGR in revenue globally.

Application Services/Software as a Service (SaaS)

  • SaaS-based applications are expected to grow from $11.8B in 2012 to $26.5B in 2016, generating a CAGR of 17.4% globally.  Gartner tracks ten different categories of SaaS applications in this latest forecast with CRM, ERP, and Web Conferencing, Teaming Platforms, and Social Software Suites being the three largest in terms of global revenue growth.
  • The three fastest-growing SaaS areas include Office Suites (40.7%), Digital Content Creation (32.2%) and Business Intelligence applications (27.1%) having the highest CAGRs from 2011 through 2016.
  • SaaS-based CRM will see the largest global revenue growth of all categories, increasing from $3.9B in 2011 to $7.9B in 2016, achieving a 15.1% CAGR worldwide.
  • Web Conferencing, Teaming Platforms, and Social Software Suites will grow from $2B in 2011 to $3.4B in 2016, generating an 11.2% CAGR.  Gartner is including Enterprise 2.0 applications in this category.
  • Supply Chain Management (SCM) is an area that Forrester, Gartner, IDC and others have predicted significant growth in.  Gartner’s latest forecast for SaaS-based SCM is $1.2B spent in 2011 growing to $3.3B in 2016, representing a 21.1% CAGR.

Application Infrastructure Services/Platform as a Service (PaaS)

  • Growth rates by PaaS subsegment include the following: Application Development (22%), Database Management Systems (48.5%), Business Intelligence Platform (38.9%) and Application Infrastructure and Middleware (26.5%).
  • Application Infrastructure and Middleware is expected to be the largest revenue source in PaaS for the next four years.  Gartner reports this subsegment  generated $649M in 2011, projected to grow to $2.1B in 2016, generating $1.5B in revenue and a 26.5% CAGR.

System Infrastructure Services/Infrastructure as a Service (IaaS)

  • With a projected CAGR of 41.7%, this segment is the fastest growing of the five Gartner included in their public cloud forecast.  From $4.2B in revenue generated in 2011 to $24.4B in 2016, IaaS is expected to grow by just over $20B in the forecast period globally.
  • CAGR by IaaS segment from 2001 to 2016 include Compute (43.2%), Storage (36.6%) and Print (16%).
  • The Compute subsegment is expected to see the greatest revenue growth globally, growing from $3.3B in 2011 to $20.2B in 2016, generating a 43.2% CAGR.

Cloud Management and Security Services

  • Comprised of Security, IT Operations Management and Storage Management, Cloud Management and Security Services generated $2.3B in 2011 with a forecast of $7.9B in 2016, generating a 27.2% CAGR.
  • IT Operations Management (38.2%), Storage Management (30.6%) and Security (23.7%) each have relatively high CAGRs through 2016.

Bottom line:  Of the five areas Gartner includes in their forecast, BPaaS  and its subsegments show trending towards greater support for enterprise-wide transaction and e-commerce management. With 76% of the entire 2012 public cloud forecast being in the BPaaS segment, it is clear Gartner is seeing strong interest on the part of enterprise clients to spend in this area.

The Marketing of Cloud Multitenancy: How Early Adopters Are Killing The Hype

It’s impressive how quickly the teams evaluating CRM cloud-based applications are learning how to deflate the hype surrounding multitenancy.

One gets the impression that hype-hunting has now become a sport in these teams.  In engineering-centric companies it’s a badge of honor to find out just how multitenant a cloud-based application or platform is.  Multitenancy isn’t the only area they are looking at, but given the massive amount of hype surrounding this issue on the part of vendors, it generates more attention because evaluation teams are skeptical.

Teams evaluating CRM applications aren’t satisfied with an easily customized and used graphical interface or series of workflows, they are getting more interested in the architecture itself .  In some cases they’ve been burned by claims of an application being SaaS-based when in fact the architecture is a glorified series of Citrix-like sessions running in the background or worse.  I have seen a healthy amount of skepticism in the evaluations going on right now and recently completed of SaaS applications and entire cloud platforms.  Gartner’s inquiry calls from corporate accounts must be accelerating as their clients look for guidance on how to sort out the multitenancy hype.

CRM, Multitenancy and the Hype Cycle for Cloud Computing

Gartner’s search analytics show that cloud computing and related terms had 29,998 searches in the last twelve months with cloud computing alone generating 10,062 searches.  SaaS and related terms had a search volume of 19,000.  These terms are among the most popular across all Gartner search terms for the last twelve months.  In comparison, CRM had over 42,000 searches in the same period.

It’s in this area of CRM applications where multitenancy has gone into hype overdrive. Looking for differentiators, some CRM vendors are claiming not just multitenancy – but their specific brand of it.  This confuses their prospects, which immediately energizes evaluation teams to do a more thorough job than they have ever done before.  By claiming their own type of multitenancy, CRM vendors are ironically not just slowing down their own sales cycles, they are making the entire industry slow down.  No wonder Gartner places multitenancy along the Peak of Inflated Expectations in the latest Hype Cycle for Cloud Computing which is shown below.

Making Sense of Elasticity and Multitenancy

It’s paradoxical that enterprise software vendors, especially those selling SaaS-based CRM applications,  are attempting to turn multitenancy into a differentiator.  What is needed is a greater focus on usability, flexibility in aligning workflows to specific needs, and better enterprise integration technologies.  Sell the value not the product features.

Given the confusion differentiating on multitenancy is creating and the calls Gartner is getting on this issue, they published Gartner Reference Model for Elasticity and Multitenancy.  It includes what Gartner believes a cloud services provider must implement in terms of a multitenant service in addition to what SaaS-based applications need to provide.  Here are their checklists for each area:

Multitenancy Service Requirements for Cloud Services Providers

  • Isolation of tenant data
  • Isolation of the tenant workspace (memory)
  • Isolation of tenant execution characteristics (performance and availability)
  • Tenant-aware security, monitoring, management, reporting and self-service administration
  • Isolation of tenant customizations and extensions to business logic
  • Continuous, tenant-aware version control
  • Tenant-aware error tracking and recovery
  • Tracking and recording of resources use per tenant
  • The ability to allocate resources to tenants dynamically, as needed and based on policy Horizontal scalability to support real-time addition/removal of tenant resources, tenants or users without interruptions to the running environment

Multitenancy in Cloud Application Services (Software as a Service) Applications

  • Be available 24/7, because of the potential global user base
  • Adopt new versions without disrupting the continuous operations of tenants, and preserve user customizations
  • Scale up or down on demand
  • Allow individual rollback and restore for each tenant
  • Not allow a “noisy neighbor” tenant to affect the performance of other tenants, or increase their costs
  • Be accessible from various locations, devices and software architectures to meet potentially global demand
  • Offer tenant-aware self-service

Gartner also released their Reference Architecture for Multitenancy, which is shown below.  One of the key assumptions of this model is that multitenancy is a mode of operation where multiple, independent and secured instances of applications run in a shared environment.  The model includes the seven different models of multitenancy Gartner has seen in their research.  These seven models, listed across the top of the model beginning with Shared Nothing and progressing to Custom Multitenancy are across the top of the model.

The majority of enterprises I’ve worked with are looking to the Shared Hardware approach in an attempt to create backward compatibility to their legacy applications via Virtual Machines. Another area of interest is the Shared Container approach which relies on a separate logical or physical instance of a DBMS, and often isolates its own business logic.  This is ideal for distributed order management systems and SaaS-based ERP systems for example.  Yet the legacy application support in this type of multitenancy can get expensive fast.

Shared Everything Multitenancy is ideal for quickly on-ramping and off-ramping applications, tenants and individual system users and is what nearly all enterprise vendors claim to do.  In reality only a handful do this well.  This approach to multitenancy is based on the Shared Container approach including support for shared DBMS sessions.  Salesforce.com’s Force.com platform, VMWare WaveMaker and Zoho Creator are all examples of companies who have successfully delivered Shared Everything multitenancy.

With so much to gain by positioning an application or solution suite in the 6th and 7th models, vendors are rushing to define their own versions of Shared Everything and Custom Multitenancy.  The land grab is on in this area of the multitenancy market right now.  IBM, Microsoft and Oracle are all expected to endorse and eventually have many of their cloud-based applications in the Shared Everything model.  Each of these companies and many others will have a multi-model based approach to selling multitenancy as well.

Gartner Reference Model for Elasticity and Multitenancy

Source:  Gartner Reference Model for Elasticity and Multitenancy

Bottom line: Enterprise software vendors can accelerate evaluation cycles and sell more by differentiating on the user experience and value delivered instead of trying to create fear, uncertainty and doubt (FUD) by creating their own definition of multitenancy.

Roundup of SaaS ERP Forecasts and Market Estimates, 2012

The latest round of SaaS ERP market forecasts are more grounded in the reality of CIO priorities and committed projects in 2012 than ever before.  And this is good news for the many vendors competing in the Financial Management Systems (FMS), Human Capital Management (HCM) and Manufacturing segments of the SaaS ERP market.

Two weeks ago in Houston I interviewed twenty-five different CIOs, IT Directors, CEOs and CTOs as part of a persona research study I am doing.  Their take on SaaS ERP was consistent with what this round-up shows, namely this type of SaaS application is best suited for extending beyond, not replacing, the main ERP systems and platforms.   I concentrated on SaaS ERP adoption in manufacturing and learned the following during my interviews:

  • Usability and speed of deployment are the two most common benefits CIOs mentioned in my survey during Convergence.  The economics of cloud computing is a topic that CFOs love to talk about, especially in the areas of value-based pricing and how that is determined.
  • When asked what kept them up at night, CIOs said it was the thought of a call from their boss (often the CFO) that a cloud system had been compromised or had completely gone down.  Security and reliability are holding back CIOs in manufacturing from adopting SaaS-based ERP systems more pervasively in their companies.
  • CIOs from aerospace and defense companies get the benefits of cloud computing, yet they have much bigger issues to deal with right now, like replacing financials in their existing ERP system and staying in compliance to government requirements.  Earned Value Management is a major focus they have as well.  SaaS-based ERP systems are interesting to them; they however would require a completely enclosed, locked-down implementation due to security requirements.
  • There are vast differences in how CIOs view cloud computing – something that the following forecasts don’t really capture.  For the CIOs who are strategists, cloud computing in general and SaaS ERP specifically is a consideration given the agility and time-to-market, providing customization is held to a minimum.  CIOs who came up through IT have a healthy degree of skepticism and see SaaS ERP as potentially useful for scaling out an operation yet never being the primary financial system.

Here are the latest SaaS ERP forecasts and market estimates:

  • Gartner released their latest SaaS revenue forecast last week predicting revenue will reach $14.5B this year, a 17.9% increase from 2011 of $12.3B, with strong growth predicted through 2015 when the market is expected to be $22.1B. Source: http://www.itjungle.com/tfh/tfh040212-story08.html
  • In the report Market Trends: Cloud Computing and SaaS Adoption in Manufacturing and Natural Resources, Worldwide, 2012 Gartner is predicting  59% of manufacturers will adopt IaaS during the 2011 – 2015 timeframe and 47% will be either piloting or using SaaS-based applications.  Gartner cites the need for greater business and supply chain agility as the factors driving this rapid adoption.  The following figure is from the Gartner report  Market Trends: Cloud Computing and SaaS Adoption in Manufacturing and Natural Resources, Worldwide, 2012.
  • Forrester forecasts SaaS ERP spending staying at 2% of the global ERP market, while Gartner forecasts 7% through 2012.  Gartner is projecting Project and Portfolio Management (29.1%) and Supply Chain Management (22.1%) will see the greatest growth rates through 2015.  Supply Chain Management is expected to reach $2.7B in revenue by 2015.  The Total Software Revenue Forecast for SaaS Delivery Within Enterprise Software is shown in the following table.  Source: Forecast: Software as a Service, Worldwide, 2010-2015, 1H11 Update Published: 22 June 2011 Analyst(s): Sharon A. Mertz, Chad Eschinger, Tom Eid, Chris Pang, Laurie F. Wurster
  • Gartner, IDC and Forrester all predict that Human Capital Management (HCM) will see the broadest adoption of all SaaS-based ERP components through 2015.  Vendors in this category include ADP, Concur, Cornerstone onDemand, HumanConcepts, Infor, Kenexa, Lumesse, Saba, SilkRoad, Sonar6, SuccessFactors, SumTotal Systems, Taleo, Ultimate Software and Workday.  Based on a recent Gartner Spending and Usage of SaaS Survey, 39% of manufacturers are piloting or using SaaS-based financials followed by 37% using Expense Management.The following figure illustrates their forecast, from the report  Market Trends: Cloud Computing and SaaS Adoption in Manufacturing and Natural Resources, Worldwide, 2012
  • Gartner’s IT Market Clock for ERP Platform Technology indicates that multitenant SaaS-based ERP is maturing rapidly, driven by time-to-market and cost advantages. The IT Market Clock is shown below, indicating SaaS ERP-based systems position relative to other ERP platforms now in use.  Vendors including  Epicor Express Editions, Glovia, Kenandy, NetSuite, Plex Systems, and SAP Business ByDesign compete in this segment.Source: IT Market Clock for ERP Platform Technology, 2011 Published: 19 September 2011 Analyst: Jim Shepherd.

Gartner has also compiled a Market Clock Recommendation Summary which is shown in the following table.  Of the CIOs I’ve spoken with during the persona research, the description of Multitenant SaaS is accurate.  No CIO I’ve spoken with is willing to bet their job on a rip-and-replace strategy for SaaS ERP; yet many are willing to extend their existing ERP systems using SaaS implementations to get up and running quickly at lower cost.  The one caveat nearly everyone mentions is little or no customization is necessary for SaaS ERP systems to be even evaluated by their companies.  Slight configuration is expected; however in-depth customization is not.

Bottom line: The persona research completed shows that the SaaS-based ERP growth is being helped by the transition occurring in the CIO ranks today.  More of them are strategists, who are expected to make business strategies happen, over and above just keeping the system dial tone on in their enterprises.

How Cloud Computing And ERP Mobility Are Reordering Gartner’s Hype Cycle for ERP

A good friend of mine recently became CIO of a financial services firm and was given his first major project last month: make the complete accounting, financial, and loan provider data and applications available 24/7 on any iPad or Android-based tablet from any office, at any time.

The majority of loan provider applications are cloud-based and his company is running NetSuite.  His corporate office is in Asia and cloud-based applications made it possible for the company to launch and operate in California within months.   He’s been given six months to transform this mobile vision into reality.

Another CIO of a major A&D manufacturer I recently visited wants vendors to challenge him more to get greater value from his investments in legacy data and ERP systems. Using ERP to run batch reports alone has nearly caused project schedules to slip, so the focus internally is on real-time system integration of project management and accounting systems.  He’s also been given the task of revamping accounting and financial systems by October, 2012, and they just started late last year.

Gartner’s Hype Cycle for ERP 

Considering these two extremes in the context of the Gartner Hype Cycle for ERP (shown below) and the recent report SaaS and Cloud ERP Trends, Observations, and Performance 2011  (free for download until January 9, 2012) published by Aberdeen last month several take-aways emerge.

  • CIOs are under increasing pressure in 2012 to enhance, modify even replace existing ERP systems while standardizing technology across the enterprise at the same time.  The most risk-averse way around this is to add applications to single instance ERP backbone systems, with analytics and Business Intelligence (BI) being the among the most in demand.
  • Cloud-based ERP in the Enterprise and Small & Medium Businesses (SMB) are accelerating along the Hype Cycle faster than Gartner indicates.  Enterprises are using Cloud-based ERP systems as part of their two-tier ERP system strategies due to the Total Cost of Ownership (TCO) and time-to-deploy advantages, and the flexibility of tailoring everything from user interfaces to workflows to their specific requirements.  Highly specialized Cloud-based ERP suites including those from Plex Systems are gaining traction due to their expertise in specific industries and the compliance-related challenges inherent within them. In SMBs, the cost and time-to-deploy are two major drivers with concerns over security being the biggest impediment to growth.  Gartner reports that they are seeing Cloud-based ERP adoption fastest in companies with fewer than 200 users overall.
  • Cloud-based ERP systems most often considered in industries that have high variable costs, rapid transaction cycles and tend towards higher Return on Invested Capital (ROIC).  Based on the research SaaS and Cloud ERP Trends, Observations, and Performance 2011 the industries who are the most willing to consider Cloud-based ERP versus on-premise are Financial Services (22% SaaS versus 44% on-premise); Healthcare (42% SaaS versus 58% on-premise); and Professional Services (56% SaaS versus 58% on-premise).
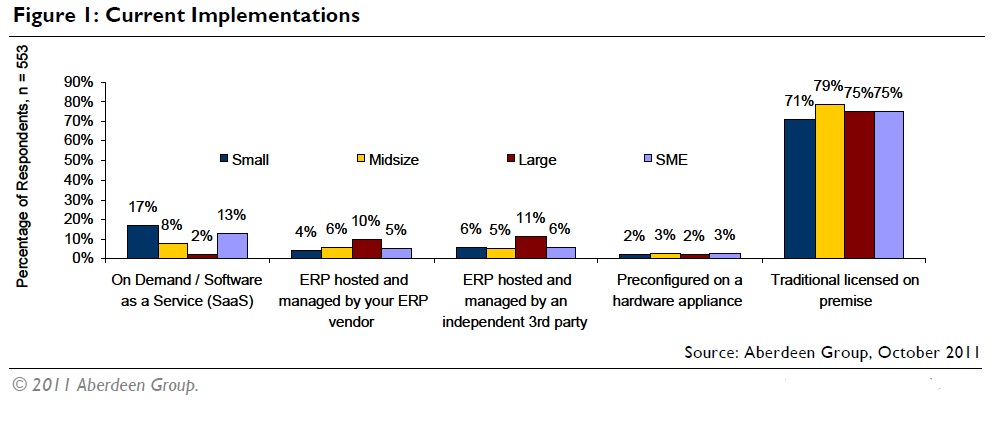
  • Large companies (over $500M in annual revenue) using Cloud-based ERP systems are opting for hosted deployments managed by their ERP vendor (10%) or an independent 3rd party (11%), with just 2% relying on a SaaS platform. Aberdeen defined small organizations as those with annual sales under $50M, midsize organizations having annual sales of $50M – $500M. The following is from SaaS and Cloud ERP Trends, Observations, and Performance 2011:
  • ERP mobility will be a dominant force from the shop floor to each sales call where quotes, orders and contracts deliver real-time order and pricing updates.  How a given manufacturer chooses to sell is even more important than what they sell in many industries. Equipping manufacturing, quality assurance, production scheduling, procurement and sales to have immediate data on what’s going on with orders, customers and suppliers is critical.  For the sales and service teams, real-time data is the fuel they run on.  There’s a chronic time shortage in many, many companies right now, and bringing greater ERP mobility from the shop floor to the sales call will increasingly be seen as a means to lessen the time crunch.  2012 is the year where mobility gets real across the enterprise with solid performance numbers being generated as a result.  For companies with large sales forces and service organizations, integrating to key ERP systems to gain real-time data will quickly lead to increased sales and higher gross margins on service and warranty repairs.
  • Gartner predicts that by 2015 enterprises who are successfully using extreme information management strategies (Big Data) will outperform competitors in their industry sectors by 20% in every available financial metric.  The following is the Priority Matrix for ERP, 2011 showing what Gartner believes to be transformational technologies and strategies in ERP.

SaaS-based ERP Systems are Business Process Stress Tests in Progress

Bottom line: Signing up for an Amazon AWS account is faster than creating a profile on Expedia. As a result, there are dozens of SaaS start-ups in the analytics, CRM, social CRM, ERP, supply chain management and many other areas of enterprise software. The ones that are going to make it already have a very clear vision of which complex, challenging, impossible business processes their customers face that they can standardize on, drive down cost per user per month down, and build a real business on.

Read more